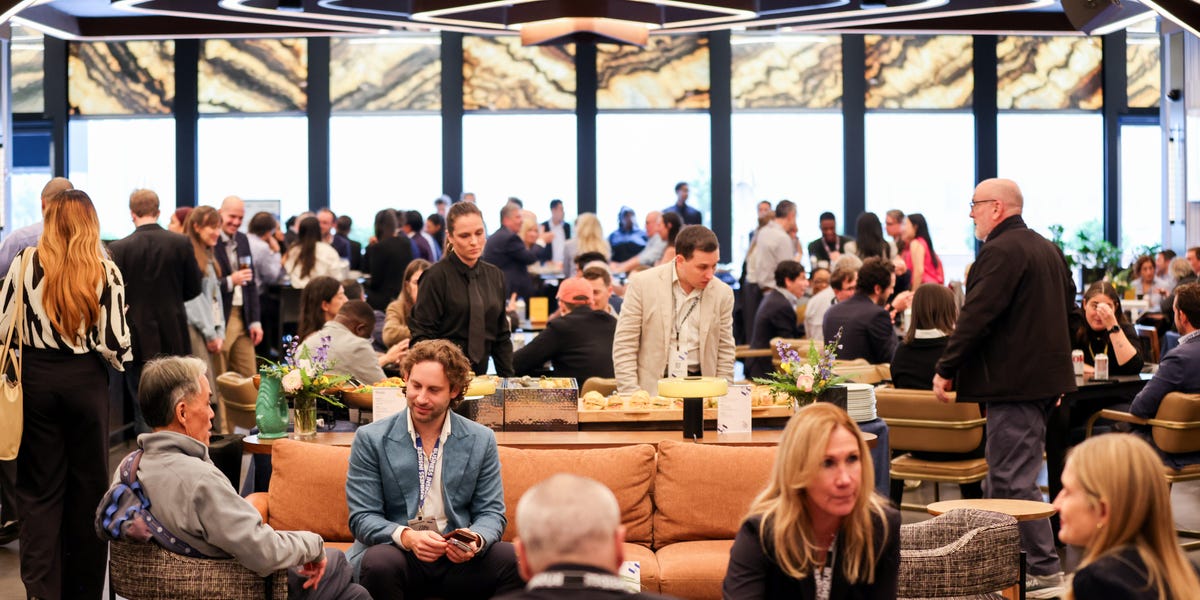
What a veteran bond investor is watching as sharp interest rate moves roil markets By William Edwards You're currently following this author! Click to unsubscribe from email alerts. Table discussions underway at Business Insider's "The Long Play" event in New York on October 29, 2026.
Carl Timpone/BFA The bond market has been in sharp focus in recent months. While rates have edged down below 5% again as investors dump tech shares and head for the safety of fixed income, higher yields may be here to stay for a while. Interest rates have moved higher all along the yield curve as sticky inflation is prompting the Fed to take action on short-term rates and bond investors to demand higher returns on the long end.
Insatiable demand for capital from AI builders and governments around the world are also pushing rates up. All of this is throwing a wrench into the AI trade and the outlook for the bull market. Higher rates could curtail borrowing and mean less spending, while also raising costs for companies that still need to tap the debt markets.
This is twisting the fragile economics of the AI buildout and causing investors to question how huge capex may ultimately pay off. To help make sense of all the bond-market volatility and the risks facing investors, our senior economy editor Ryan Kailath and I sat down with John Sheehan at Business Insider's " The Long Play " event in New York on Thursday. Sheehan, a portfolio manager on the strategic income strategy at Osterweis Capital Management, joined us for a lunchtime discussion with conference attendees about rates.
Attendees gather at The Long Play in New York. Carl Timpone/BFA Here are some of the questions that came up during the conversation, and how Sheehan is thinking about them. How concerned with rising borrowing costs should we be as it relates to the AI trade?
Will we see any defaults? Sheehan said that the constant issuance of new bonds was going to keep pushing up interest rates, and that would likely cause some firms to go under eventually. "Anytime we get some stability, or even bonds start to do a little better, you're going to see more supply dropped in and sort of cap your upside," he said.
In other words, when yields start to fall, companies see it as an opportunity to borrow more, which then helps to push up rates again. "History would tell us that there are going to be some winners and losers, and there's most likely going to be some that end up in trouble," he said. Naturally, he said some high-yield bond issuers are at the highest risk of not being able to meet their debt obligations.
Can we expect things to unravel further if the Fed hikes rates in December? Fed chair Warsh acknowledged the Septermber rate hike's impact on the neocloud volatility in October, but Sheehan pushed back on the notion that a 25-basis-point hike is causing trouble in for AI firms. "Some of them are trading at 15%, so I don't really know how much 25 basis points of the fed funds will do," he said.
"Our macro view is that the Fed is still very accommodative." How many rate hikes do you see in the next 12 months? Roughly going with the market consensus or slightly below it, Sheehan said he sees one to two hikes coming within the next year. According to the CME FedWatch tool, markets are pricing in a 35% chance of two more hikes by the October 2027 meeting.
However, markets also see a 37% chance that the central bank hikes at least three more times by then. What's the way out of higher rates on the long end of the yield curve? Or will yields keep moving higher from here?
Sheehan said he sees little stopping the upward pressure on rates. AI borrowing, government borrowing, and oil prices are all trending toward higher yields. Growing US government debt levels are a problem in particular, he said, as the government needs to constantly borrow more to keep up with rising rates, which creates a feedback loop.
"The portion of the budget that goes toward interest expense continues to grow, which means more borrowing," he said. "So I can't see long rates materially lower from here with inflation where it is, how sticky it is," Sheehan added. Where are you investing in this environment of rising yields?
Rising rates are a double-edged sword for bond investors — they mean that bonds you already hold depreciate in value, but any new bonds that you buy will deliver more attractive coupons. To get the best of both worlds, Sheehan said he's staying at around the 1.75-year average duration mark, less than his benchmark's duration of around 3 years. That way he locks in higher yields, but doesn't deal with too much duration risk if rates go higher.
Less than two years is a lot less painful to wait out than 10 years. Read next Business Insider tells the innovative stories you want to know Business Insider tells the innovative stories you want to know Business Insider tells the innovative stories you want to know Business Insider tells the innovative stories you want to know William Edwards You're currently following this author! Click to unsubscribe from email alerts.
William Edwards is a senior investing reporter at Business Insider primarily covering the US stock market and the broader economy. He's interviewed some of the most influential voices in the market, including Joseph Stiglitz , Jeremy Grantham , Rick Rieder , Rob Arnott , Savita Subramanian , Nouriel Roubini , Ken Rogoff , Mike Wilson , Claudia Sahm , Albert Edwards, Andrew Ross Sorkin , Ben Snider , and more. William launched BI's annual Oracles of Wall Street list ( 2023 , 2024, 2025 ), highlighting top calls from strategists, economists, and analysts.
He also writes BI's Where to Invest $10,000 column, and contributes to the First Trade newsletter. Prior to Business Insider, William covered the US economy for Bloomberg News in Washington, DC and contributed to TV tech coverage for CNBC in San Francisco. He has also spent time studying or reporting in France, Germany, and Tunisia.
He is based in New York. Investing The Long Play Interest Rates More Federal Reserve
Source: Business Insider